Welcome to our live ASX coverage for Tuesday, October 20. Expect a high volume of posts pre-market and more periodic updates throughout the day. We’ll be wrapping the blog up around 2:00 pm AEDT. Let us know how we can make it even better.
ASX 200 pares losses as healthcare extends rally
[2:20 pm] That’s a wrap! The S&P/ASX 200 is down 63 points or 0.72%, recovering from a session low of -1.11%. Energy stocks are still trading near their worst levels, banks have made a small bounce off lows of 1.7%, while materials have clawed back almost half of an intraday fall of 2.1%. Staples are holding near session highs, and healthcare has extended its gains to be up 1.9% year-to-date, a sharp turnaround from its 34% slide in the year to 3 June.
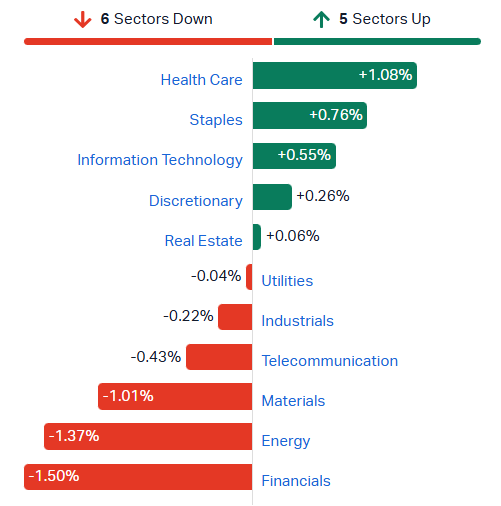
S&P/ASX 200 sectors (Source: Market Index)
Overall, markets are turning defensive, with healthcare and staples the two best-performing sectors over the past month, up 7.6% and 7.0% respectively. Discretionary stocks have also caught a decent bid in recent weeks, as a roughly 16% pullback came to a halt and easing rate hike bets fuelled a rotation back into battered retailers. It’s an awkward market. Defensives are being bought even though CSL is forecast to deliver only around 5% earnings growth over the next two years and staples are trading on elevated multiples, suggesting investors are happy to pay almost any price for safety. Meanwhile, the much-loved miners are back on the defensive.
CSL’s comeback rolls on, more than doubling from June low
[1:43 pm] Just how far can CSL re-rate? The stock is up another 1.2% to $196.44, taking its year-to-date gain to 14% and its rebound from the 3 June low of $92.27 to 113%.
CSL had already rallied around 47% from its lows heading into its FY26 result on 14 August, which came in slightly ahead of expectations. The company guided to flat FY27 revenue and underlying NPAT growth of about 5%, ahead of consensus for around 2% EPS growth and Macquarie’s forecast for flat earnings. It’s pretty wild that a slightly better-than-expected guide was all it took to reignite an epic comeback. Even so, the stock trades on around 15x forward earnings, with analysts expecting roughly 5% annual earnings growth over the next two years.
Energy stocks retreat from six-month high
[1:39 pm] Energy stocks are pulling back across the board, with refiners and coal miners giving back recent gains. The sell-off follows a 2.2% rally in the S&P/ASX 200 Energy Index on Monday to its highest level since April.
|
SMR |
Stanmore Resources |
-6.1% |
$2.63 |
-4.0% |
12.9% |
|
YAL |
Yancoal Australia |
-5.7% |
$5.93 |
-1.2% |
19.1% |
|
STX |
Strike Energy |
-4.8% |
$0.10 |
-13.0% |
-4.8% |
|
ALD |
Ampol |
-4.2% |
$40.18 |
-6.6% |
25.8% |
|
NHC |
New Hope Corporation |
-3.1% |
$5.99 |
-6.6% |
49.4% |
|
WHC |
Whitehaven Coal |
-2.8% |
$7.71 |
-5.1% |
-0.8% |
|
KAR |
Karoon Energy |
-1.1% |
$1.73 |
-5.7% |
12.0% |
|
WDS |
Woodside Energy Group |
-1.1% |
$33.66 |
2.3% |
41.8% |
|
VEA |
Viva Energy Group |
-0.8% |
$3.10 |
0.2% |
49.5% |
|
STO |
Santos |
-0.8% |
$9.25 |
7.8% |
49.7% |
|
BPT |
Beach Energy |
-0.3% |
$0.90 |
3.1% |
-22.9% |
SoftBank credit risk hits four-year high on AI funding strain
[1:25 pm] The cost of insuring SoftBank’s debt against default has climbed to its highest in nearly four years, as CoreWeave’s troubles put a spotlight on the borrowing behind the AI boom.
-
SoftBank’s five-year credit default swaps rose to 432bps on Tuesday, the highest since early November 2022
-
Spreads have widened by more than 30bps since moving above 400bps a week earlier
-
SoftBank is weighing a takeover of Allied Universal, the largest US security firm, as financing costs rise
-
Bloomberg Intelligence’s Sharon Chen expects at least US$6bn of cash outflow in the year to March 2027, with further AI investment adding to funding needs
-
Chen said SoftBank would need fresh funds for the deal, with its loan-to-value ratio potentially moving toward its self-imposed 25% ceiling
-
SoftBank shares have fallen about 50% from their June high
Source: Bloomberg
Asian stocks fall as US chip rally fails to carry over
[1:00 pm] Asian stocks diverged from Wall Street’s chip-led rebound as investors held back ahead of key tech earnings from Meta and Tesla this week.
-
The MSCI Asia Pacific Index fell 0.8%, with nine of its 11 sectors lower and two stocks falling for every one that rose
-
South Korea’s Kospi led losses with a 2.7% drop, as SK Hynix headed for its lowest close since April
-
Hong Kong’s Hang Seng fell 1.1%, Japan’s Topix lost 0.9% and the ASX 200 slipped 0.7%
-
The US 10-year Treasury yield held at 5.13% after climbing 7bps overnight, while Australia’s 10-year yield rose 4bps to 5.26%
-
HSBC’s Frederic Neumann said “The relief rally seen in US tech stocks overnight is failing to carry through to Asia”
Source: Bloomberg
Supermarket rally lifts staples to highest since 2023
[11:53 am] The S&P/ASX 200 Consumer Staples Index is up 1.1% to its highest level since April 2023, extending a gain of just over 5% so far this month. Woolworths is trading at its highest since August 2021, while Coles looks poised to break out of its recent range and into fresh all-time highs.
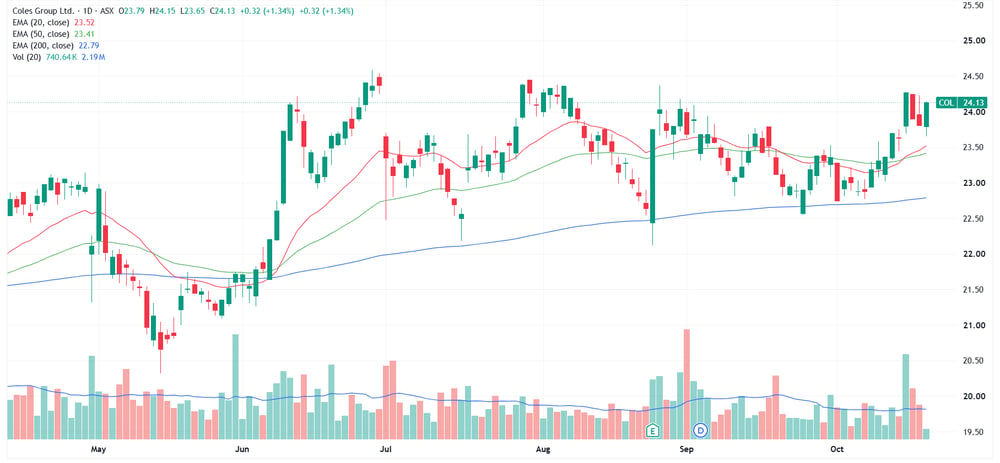
Coles daily price chart (Source: TradingView)
The rally leaves the supermarket giants at an awkward juncture. Coles trades on a forward PE of around 25x, with Bell Potter forecasting 8.5% earnings growth in FY27, while Woolworths trades on around 26x with 13% growth. In FY28, growth is forecast at about 9% for Coles and 4% for Woolworths. Overall, the two have run up pretty hard in recent weeks, trading at fairly elevated valuations, though still some decent growth forecast over the near term.
Korean neocloud Elice plunges 32% on debut
[11:54 am] Seoul-based Elice, which provides AI cloud computing and data centre infrastructure, sank on its Kosdaq debut in the latest sign of fading investor appetite for AI infrastructure listings.
-
Elice fell as much as 32% to 61,400 won in early trade, after pricing its IPO at 90,500 won, the top of its range
-
The IPO raised 201bn won (US$151m), the Kosdaq’s biggest this year, for a post-listing market cap above 1tn won
-
The retail offer was oversubscribed more than 400 times, with about 10.3tn won poured into subscription deposits
-
First-half revenue rose 200% to 34.4bn won, with the company swinging to an operating profit of 10.3bn won
-
The debut follows a string of AI infrastructure setbacks, including Firmus Grid cancelling its Sydney listing this month and AirTrunk reportedly delaying a REIT IPO
-
Petra Capital’s Albert Yong said “Sentiment toward AI infrastructure has been highly volatile and often disconnected from underlying fundamentals”
Source: Bloomberg
NAB to cut 2,500 jobs in $300m overhaul
[11:50 am] NAB is the latest major bank to slash headcount as a property downturn and tax changes weigh on mortgage volumes and competition intensifies.
-
NAB will cut up to 2,500 jobs, about 6% of its roughly 42,000 staff, targeting management and corporate roles
-
The bank will take a $300m pre-tax restructuring charge in FY27
-
About 1,500 roles are expected to go before the end of 2026
-
NAB will also reduce its reliance on external contractors and consultants, with no material impact on customer-facing roles
-
The cuts follow similar moves at rivals, with ANZ cutting 3,500 roles and 1,000 contractors last year and Westpac trimming more than 1,500 roles
Source: Bloomberg
Miners dip as BHP copper miss weighs
[11:47 am] Miners are on the backfoot again, with the S&P/ASX 200 Materials Index down 1.8%, after gaining 3.2% in the prior two sessions. Gold, rare earths, coal, copper and uranium equities are trading broadly lower amid a relatively soft overnight session for commodity prices. BHP is the main drag on the Materials Index after its September quarter copper production fell 19% to 400.7kt on planned grade declines, maintenance and weather disruptions.
|
BHP |
BHP Group |
-2.0% |
$59.26 |
-2.7% |
30.2% |
|
RIO |
Rio Tinto |
-0.8% |
$154.21 |
-8.0% |
5.0% |
|
FMG |
Fortescue |
0.5% |
$15.33 |
-9.4% |
-30.3% |
|
NST |
Northern Star |
-2.5% |
$24.41 |
10.9% |
-0.6% |
|
EVN |
Evolution Mining |
-3.5% |
$12.08 |
-10.6% |
-3.9% |
|
S32 |
South32 |
-2.1% |
$4.42 |
-9.7% |
24.4% |
|
BSL |
Bluescope Steel |
1.0% |
$32.83 |
5.0% |
36.4% |
|
LYC |
Lynas Rare Earths |
-1.3% |
$11.20 |
-19.1% |
-9.8% |
|
SFR |
Sandfire Resources |
-2.3% |
$20.12 |
-7.0% |
12.0% |
|
PLS |
PLS Group |
-0.3% |
$2.89 |
-33.6% |
-31.2% |
|
MIN |
Mineral Resources |
-0.3% |
$44.41 |
-19.0% |
-18.4% |
|
GMD |
Genesis Minerals |
-3.4% |
$6.95 |
-6.7% |
-3.0% |
|
PRU |
Perseus Mining |
-2.9% |
$5.97 |
-8.9% |
8.3% |
|
CMM |
Capricorn Metals |
-2.1% |
$13.85 |
-6.0% |
-1.1% |
|
IGO |
IGO |
-1.2% |
$5.25 |
-26.8% |
-36.0% |
ASX 200 dips as banks and miners tumble
[11:15 am] The ASX 200 is down 75 pts (-0.85%) amid a sharp selloff for heavyweight sectors like Materials, Energy and Financials, all of which are down more than 1%.
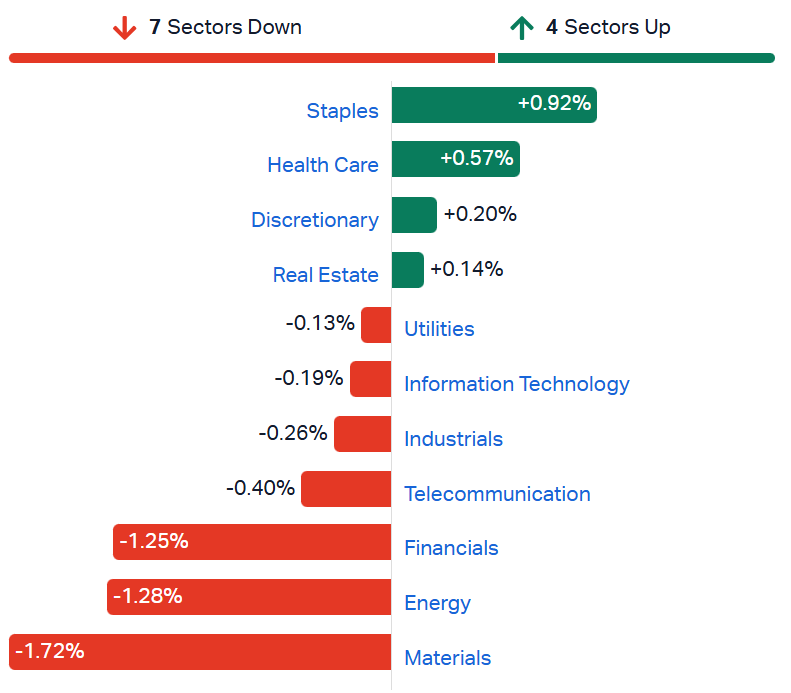
S&P/ASX 200 sectors (Source: Market Index)
Unlike recent sessions, large caps are leading the decline, with the ASX 20 down 1.0% and the ASX 50 down 0.96%. Small caps aren’t faring much better, with the Small Ords and Emerging Companies indices both down about 0.8%.
|
BHP |
BHP Group |
-2.1% |
$59.20 |
-2.8% |
30.0% |
|
CBA |
Commonwealth Bank |
-1.4% |
$153.23 |
-0.5% |
-4.6% |
|
RIO |
Rio Tinto |
-0.9% |
$154.11 |
-8.0% |
5.0% |
|
NAB |
National Australia Bank |
-2.5% |
$38.89 |
-0.5% |
-8.0% |
|
WBC |
Westpac |
-1.5% |
$34.90 |
0.6% |
-9.4% |
|
ANZ |
ANZ Group |
-1.0% |
$38.88 |
2.7% |
6.7% |
|
CSL |
CSL |
0.9% |
$195.71 |
10.1% |
12.8% |
|
MQG |
Macquarie Group |
-1.4% |
$245.89 |
2.9% |
21.1% |
|
WES |
Wesfarmers |
0.1% |
$79.00 |
8.3% |
-2.5% |
|
WDS |
Woodside Energy Group |
-1.1% |
$33.67 |
2.3% |
41.9% |
Corporate Travel extends gains after IATA guarantee release
[11:12 am] Corporate Travel Management has extended its early gains, now up 17% to $2.90, after IATA released the company’s $65 million security guarantee and restored its previous settlement terms. The change is expected to boost CTM’s working capital by about $30 million. The stock surprisingly opened 2.0% lower, and has moved pretty much vertically higher since the open.
Company page: Corporate Travel Management (CTD)
Cboe’s pre-market options session debuts with modest volumes
[11:03 am] Cboe Global Markets, the US exchange operator, has launched pre-market trading in single-stock options as US markets move toward near round-the-clock trading.
-
More than 16,000 lots traded in the first session, which ran from 7.30am to 9.25am New York time on Monday
-
Options on the Invesco QQQ Trust and iShares Russell 2000 ETFs were the most traded, followed by Tesla
-
The volumes were tiny compared with the roughly 71m contracts that typically trade in the US options market each day
-
Several exchanges are preparing to allow nearly 24-hour stock trading from December, part of a broader push to extend trading hours
-
Piper Sandler’s Patrick Moley said “I don’t expect it to be needle moving coming out the gate”
Source: Bloomberg
Top ASX 200 gainers
[10:35 am] Ingenia tops the leaderboard after Warburg Pincus extended their process deed negotiations to 23 October, while a few tech and healthcare stocks catch a bid.
|
INA |
Ingenia Communities Group |
8.1% |
$4.59 |
9.4% |
-11.8% |
|
ASB |
Austal |
5.4% |
$4.12 |
-9.8% |
-38.7% |
|
HUB |
Hub24 |
4.1% |
$67.21 |
-2.5% |
-30.1% |
|
ARF |
Arena REIT |
3.2% |
$2.57 |
19.0% |
-27.8% |
|
GDG |
Generation Development Group |
3.0% |
$3.14 |
8.3% |
-46.7% |
|
TUA |
Tuas |
2.9% |
$1.78 |
-20.8% |
-74.8% |
|
360 |
Life360 |
2.5% |
$20.23 |
6.0% |
-37.2% |
|
COH |
Cochlear |
2.1% |
$135.37 |
-0.7% |
-48.1% |
|
XRO |
Xero |
2.0% |
$61.54 |
-5.8% |
-46.0% |
Top ASX 200 losers
[10:35 am] Materials, energy and financials are all down more than 1% in early trade, with gold miners leading the losses.
|
MI6 |
Minerals 260 |
-5.2% |
$0.74 |
-21.8% |
75.0% |
|
KCN |
Kingsgate Consolidated |
-5.0% |
$4.40 |
-18.4% |
-21.4% |
|
GQG |
GQG Partners |
-4.6% |
$1.03 |
-1.9% |
-41.1% |
|
ALD |
Ampol |
-4.1% |
$40.22 |
-6.5% |
25.9% |
|
OBM |
Ora Banda Mining |
-4.0% |
$1.33 |
-11.7% |
-13.4% |
|
PDI |
PDI Gold |
-3.8% |
$4.14 |
-13.3% |
13.3% |
|
MP1 |
Megaport |
-3.6% |
$15.35 |
-12.5% |
35.3% |
|
RSG |
Resolute Mining |
-3.6% |
$1.09 |
-19.6% |
-11.4% |
|
PNR |
Pantoro Gold |
-3.5% |
$2.78 |
3.0% |
-43.3% |
|
IPX |
Iperionx |
-3.4% |
$1.97 |
-32.1% |
-64.2% |
Corporate Travel and Gentrack lead early catalyst movers
[10:17 am] Corporate Travel and Gentrack jumped at the open on contract and balance sheet news, while softer quarterly updates weighed on BHP, Regis and Bellevue.
-
Corporate Travel (+8.1% to $2.68): IATA released its $65m security guarantee and restored previous settlement cycles, lifting working capital by about $30m
-
Gentrack (+7.8% to $3.58): Signed Momentum Energy to its g2 billing platform, covering more than 200,000 meter points across Australia
-
Hub24 (+4.6% to $67.51): Q1 platform net inflows fell 23% to $4.0bn, but advisers rose 12% to 5,860 and market share lifted to 10.1%
-
Judo Capital (+2.5% to $0.94): Reaffirmed FY27 profit before tax guidance of $210-220m at its AGM, though 90+ day arrears rose to 3.16%
-
BHP (-2.2% to $59.16): Q1 copper production fell 19% to 400.7kt on grade declines, weather and the Carrapateena conveyor failure, with guidance unchanged
-
Regis Resources (-2.6% to $6.80): Q1 production of 83koz at an AISC of $3,617/oz as heavy rain delayed access to higher-grade ore
-
Bellevue Gold (-2.8% to $1.39): Q1 production fell 15% to 35,585oz on a slow contractor ramp-up, with AISC up 19% to $3,096/oz
China flags benchmark switch that could act as a rate cut
[10:13 am] The People’s Bank of China (PBOC) plans to make its overnight reverse repo rate, what it charges banks for one-day loans secured against bonds, its main policy benchmark, a shift economists say could work as a de facto rate cut.
-
Governor Pan Gongsheng said the PBOC will study switching its main policy tenor to overnight from seven days “at an appropriate time”
-
The overnight reverse repo rate was set at 1.25% in June, below the current seven-day benchmark, which Huatai Securities says would “function as a de facto rate cut”
-
Goldman Sachs’ Xinquan Chen said the PBOC could deliver part of next year’s easing through the benchmark change rather than a conventional rate cut
-
Interbank overnight borrowing costs have fallen below 1.3% this month, the lowest since May, as markets price in the shift
-
Companies with strong financials will be able to price loans off the interbank overnight repo rate, while the loan prime rate will remain for small businesses and individuals
-
A new liquidity tool will help non-bank financial institutions meet large redemption requests, aimed at stabilising the bond market
Source: Bloomberg
Melbourne auctions plunge as reserve price rules kick in
[9:22 am] Melbourne auction volumes fell sharply in the first week of Victoria’s new reserve price disclosure rules, driving the biggest weekly drop in national volumes since mid-August.
-
1,423 homes went to auction across the combined capitals, down 18.6% week-on-week and 45.8% year-on-year
-
Melbourne hosted 500 auctions, down from 703 the previous week and 1,142 a year ago, accounting for 203 of the 326 fewer auctions nationally
-
The combined capitals preliminary clearance rate rose to 51.2% from 48.8%, the highest in four weeks
-
Melbourne’s clearance rate rose to 56.2% from 54.8%, while Sydney’s lifted to 54.6% from 52.9%
-
Brisbane had the lowest clearance rate at 31.5%, well below 67.8% a year ago
-
About 1,240 auctions are scheduled this week, with Melbourne’s 489 roughly 70% fewer than a year ago
Source: Cotality
IATA releases Corporate Travel’s $65m guarantee
[9:21 am] The International Air Transport Association (IATA), the global airline industry body that runs the system travel agents use to settle ticket sales with airlines, has completed its latest financial assessment of Corporate Travel Management.
-
IATA has released the $65m security guarantee CTM provided in December 2025, while its FY25 accounts were being finalised
-
CTM’s previous settlement cycles have been restored, replacing the temporary adjusted arrangements
-
The change is expected to improve working capital by about $30m
-
CEO Ana Pedersen said “IATA’s decision is an important milestone for CTM, following the successful completion of its latest financial assessment of the Company”
Company page: Corporate Travel Management (CTD)
StepChange lifts Q1 EBITDA on Broadreach contribution
[9:18 am] StepChange’s September quarter was one of steady delivery, with its shift toward outcome-based work starting to lift margins.
-
Revenue rose 34% year-on-year to $16.8m on organic growth and the contribution from Broadreach, acquired in January 2026
-
Underlying EBITDA rose 44% to $1.4m
-
Gross margin rose to 15.2% from 14.3% in FY26 on better utilisation, contractor mix and the move to outcome-based delivery
-
Cash fell to $3.8m from $5.2m after $6.6m in deferred acquisition payments, leaving net debt of $1.2m
-
The AI Method Library grew to 130 methods from 100+ at the FY26 result, with 14 of 50 registered consultants now certified
-
FY27 priorities are unchanged, with StepChange pointing to its usual stronger second half for revenue and EBITDA
StepChange is a Perth-based SAP and digital transformation consulting firm which made its ASX debut back in July 2025 after raising $14.7m at 20 cents per share. The stock closed at 12 cents on Monday, with a market cap of approximately $19.7m.
Company page: StepChange Holdings (STH)
Hub24 inflows slow but adviser growth holds up
[9:12 am] Hub24’s September quarter net inflows slowed as tax changes weighed on IDPS flows, but the platform kept adding advisers and market share.
-
Total FUA rose 15% year-on-year to $168.6bn
-
Platform FUA rose 18% to $143.7bn, up 3% over the quarter
-
PARS FUA rose 2% to $24.9bn
-
Platform net inflows fell 23% to $4.0bn, with superannuation gross inflows up on the pcp while IDPS flows were weaker
-
Advisers using the platform rose 12% to 5,860, with 211 added in the quarter and 45 new licensee agreements signed
-
Market share rose to 10.1% from 9.0%, with HUB24 ranked first for quarterly and annual net inflows for an eleventh straight quarter
UBS forecasts FY27 platform net flows of $17.6bn, or about $4.4bn a quarter. Adviser growth is tracking ahead, with 211 added in Q1 vs UBS’s forecast of about 500 for the full year. UBS upgraded the stock to buy on 7 October with a $77.35 target, arguing the 34% YTD sell-off already prices in more downside than the fundamentals justify.
Company page: HUB24 (HUB)
BHP copper output slides 19% but guidance held
[9:07 am] BHP’s copper production fell sharply in the September quarter, though copper prices around 50% higher than a year ago provided an earnings tailwind.
-
Copper production fell 19% year-on-year to 400.7kt on planned grade declines, maintenance, severe weather in Chile and the Carrapateena conveyor failure
-
FY27 copper guidance of 1,650-1,800kt was unchanged, implying about 441kt a quarter for the rest of the year at the midpoint
-
WAIO production rose 4% to 64.3Mt, with records at both the mine and port despite a maintenance-heavy quarter
-
BMA steelmaking coal rose 1% to 4.9Mt, while NSW Energy Coal jumped 26% to 4.4Mt on higher bypass coal
-
Jansen Stage 1 is 87% complete and on track for first potash production in mid-2027
-
Two workers died at Escondida and Peak Downs during the quarter, with investigations underway
Company page: BHP Group (BHP)
Judo reaffirms FY27 guidance as arrears tick higher
[9:04 am] Judo says SMEs are turning cautious on the economy, rate rises and Budget changes, but first quarter performance has tracked in line with its FY27 assumptions.
-
FY27 profit before tax guidance of $210-220m was reaffirmed
-
Gross loans and advances reached almost $15.1bn at 30 September on robust originations and improving attrition
-
The AAA loan pipeline was $1.9bn in September at mid-4% margins, with SME caution weighing beyond normal seasonality
-
Blended lending margins were 4.1% over 1-month BBSW, while deposit margins of 73bps came in slightly better than expected
-
90+ days past due and impaired loans rose to 3.16% from 2.90% in June, still below Judo’s through-the-cycle assumption
-
The CET1 ratio eased to 12.0% from 12.4%, at the top of the 11-12% operating range, with Judo flagging scope to enhance shareholder returns over time
Judo shares have traded mostly sideways between $0.90 and $1.00 since plunging 40% on 25 June, when the bank cut its FY26 profit before tax guidance to $163-169m, down from the lower end of its previous $180-190m range.
Company page: Judo Capital Holdings (JDO)
Gentrack wins Momentum Energy billing contract
[9:02 am] Gentrack has added another Australian energy retailer to its g2 platform after a competitive evaluation.
-
Momentum Energy has signed with Gentrack to support its more than 200,000 residential and business meter points across Australia
-
Momentum will use the g2 billing platform to simplify its technology, cut its cost to serve and drive AI efficiencies
-
Gentrack’s Australian delivery record, regulatory compliance model and Salesforce integration were cited as reasons for the win
-
The contract value and term were not disclosed
-
Momentum interim CEO Danny Moore said: “This transformation represents a significant investment in the future of our business”
Company page: Gentrack Group (GTK)
Bellevue output falls on slow contractor ramp-up
[9:01 am] A slower-than-expected ramp-up by Bellevue’s new mining contractor weighed on September quarter output, with the deferred ounces expected to be recovered in later quarters.
-
Gold production fell 15% quarter-on-quarter to 35,585oz
-
AISC rose 19% to $3,096/oz, near the top of the FY27 guidance range
-
FY27 guidance was maintained at 150-170koz and AISC of $2,800-3,100/oz
-
Underlying free cash flow fell 56% to $48m on lower gold sales and capex for the contractor transition and paste plant
-
The hedge book was cut by 11.2koz to 57.5koz, with the $4,980/oz realised price including 11,150oz delivered early into hedges, and full elimination targeted in FY27
-
Cash and gold on hand rose to $213m from $206m
Company page: Bellevue Gold (BGL)
Regis builds $1.28bn cash pile despite rain-hit quarter
[9:00 am] Heavy September rain delayed Regis’ access to higher-grade open pit ore, with management pointing to a stronger second half.
-
Group gold production of 83.0koz was in line with expectations, with full year guidance maintained for both operations
-
Duketon produced 56.1koz at $3,657/oz
-
Tropicana produced 27.0koz at $3,423/oz
-
-
Group AISC came in at $3,617/oz
-
Gold sales of 74.5koz raised $454m at an average realised price of $6,088/oz
-
Cash and bullion rose 8% to $1.28bn, including the $51m Vault Minerals break fee and after $53m in tax payments
-
Fully franked final dividends of 20cps ($152m) were paid after the quarter
-
The Federal Court ruled a Section 10 declaration over part of the McPhillamys site is legally invalid, which CEO Jim Beyer said “adds important potential optionality”
Company page: Regis Resources (RRL)
Nasdaq rebounds 1.1% as chip stocks snap losing streak
[8:48 am] Chipmakers led a rebound on Wall Street after the Nasdaq’s worst week since April 2025, though most S&P 500 stocks still finished lower.
-
The Nasdaq rose 1.1% to 26,430.89, the S&P 500 added 0.4% and the Dow slipped 0.1%
-
The Philadelphia Semiconductor Index rose 1.6%, ending an eight-session losing streak, its longest in 18 years, while Intel gained 2.4% on a JPMorgan upgrade to neutral
-
Roughly 70% of S&P 500 stocks fell and the equal-weight index finished lower, per Yahoo Finance
-
Amazon jumped 5% after Morgan Stanley named it a top pick, helping consumer discretionary lead sectors with a near 3% gain
-
CoreWeave fell 0.4% despite a Goldman Sachs upgrade to buy, with the target cut to US$106 from US$139, after a 25% slump last week on debt concerns
-
Morgan Stanley’s Mike Wilson told clients: “We advise investors to be ready for either a very rapid reconciliation or a slower bleed into November because in our view, that will be the time to add risk rather than shun it”
Brent holds near US$110 as Iran’s oil exports dry up
[8:45 am] Iran’s crude exports have fallen to zero under the renewed US naval blockade, keeping Brent near five-month highs even as Hormuz traffic recovers.
-
Brent fell 0.4% to US$109.26 a barrel but swung between session highs of US$110 and lows of US$106.8
-
No tankers have docked at Kharg Island since late August, with Iran’s crude exports down from almost 1m barrels a day in July to nothing
-
25 ships were targeted in and around Hormuz in the first two weeks of October, vs 18 in all of September
-
Crude flows through Hormuz are nearing pre-war levels, topping 100m barrels last week
-
Eurasia Group lifted its odds of the conflict intensifying to 65% from 35%
-
Ukraine struck an oil terminal in St Petersburg on Sunday, while US lawmakers introduced a bill to block Trump’s Russian diesel deal
-
The US offered up to 17m barrels from the Strategic Petroleum Reserve on Friday
Copper bulls grow wary as tariff trade unwinds
[8:42 am] Traders are increasingly betting Trump won’t follow through on copper tariffs, collapsing the Comex premium that drove prices to record highs.
-
LME three-month copper was little changed at US$14,389 a tonne, after hitting a record near US$15,000 last month
-
The Comex premium over the LME has collapsed in recent weeks, accelerating after a Reuters report that tariff plans had stalled over inflation concerns
-
Macquarie says prices could crash toward US$10,000 a tonne if tariffs are ruled out, or rally to US$18,000 if announced with a lag
-
US-bound copper shipments from Africa are already dwindling as the spread narrows, according to Kpler
-
The Commerce Department recommended phased levies of 15% in 2027 and 30% in 2028, potentially starting as soon as 1 January
Source: Bloomberg
China’s Q3 growth beats as exports surge
[8:41 am] China’s economy picked up pace in the third quarter as strong foreign demand for tech goods offset a deepening property slump.
-
GDP grew 4.5% year-on-year vs 4.4% ests, up from a three-year low of 4.3% in Q2
-
The monthly trade surplus hit a record US$133.5bn
-
A deepening property slump and sluggish consumer demand continue to weigh
Indonesian stocks plunge 5% on MSCI downgrade threat
[8:40 am] Indonesia’s benchmark hit a six-year low after MSCI proposed stripping the country of emerging market status.
-
The Jakarta Composite fell more than 5% to its lowest level since October 2020
-
MSCI proposed reclassifying Indonesia directly from emerging market to standalone status
-
Goldman Sachs estimates full removal could trigger about US$5.6bn in passive outflows, equal to 18 days of average trading volume
-
A final decision is due by June, hinging on improvements in market governance and transparency
Source: Yahoo Finance
Good morning!
[8:29 am] ASX 200 futures are down 77 pts (-0.87%). Here’s what happened overnight:
-
Chipmakers led a tech rebound that lifted the Nasdaq and S&P 500, though most S&P 500 stocks fell and the Dow finished slightly lower
-
S&P 500 (+0.41%), Equal-weight S&P 500 (-0.32%)
-
Nasdaq (+1.11%), Dow (-0.07%) and Russell 2000 (+0.25%)
-
US yields higher across the curve, with the 2-year up 6 bps to 4.77%, the 10-year up 6 bps to 5.14% and the 30-year up 5 bps to 5.47%
-
-
Treasuries sold off as haven demand faded, with traders rebuilding bets on Fed hikes into next year ahead of next week’s FOMC
-
European stocks slid after violent French protests, while Brent held near US$110 as Houthi-Saudi hostilities kept Gulf supply fears elevated